A crypto exchange listing is an application to a business that receives several hundred of them a month and turns most of them down; we prepare them for the top 60 exchanges on CoinMarketCap. What decides it is rarely enthusiasm for the project; it is whether the paperwork, the token contract and the market data hold up under review. The sections below set out what a venue actually asks for, the order the work happens in, what the fees cover, and what to do when an application is declined.
Checked on 25 October 2026 against exchange listing pages and our own listing work.
Crypto listing services exist because the right exchange listing decides a project’s visibility and liquidity. Exchange listings serve as a crucial milestone in a crypto project’s journey, opening doors to wider adoption and market presence. With thousands of cryptocurrencies competing for attention, a planned cryptocurrency listing on exchange platforms is essential for standing out in this crowded marketplace.
Our crypto exchange listing service
We work across the top 60 exchanges ranked on CoinMarketCap and pick the venues that fit the token, its holders and its budget, rather than the largest names first. Binance is the exception: it accepts applications only from the founding team and blacklists projects that apply through agents, so for Binance we prepare the evidence file and the founder submits it, as our guide on how to list a token on Binance explains.
- A shortlist of exchanges by tier, with what each one asks for and how long it usually takes
- The document set: verified contract, reconciled supply table, audit, team and legal answers
- Form filling and the commercial conversation with each listing team
- Technical integration support and the first week of trading after launch
Market Making Services Available
Most serious exchanges ask about market making in the form, so we arrange it before the application rather than after it. Terms go in writing, including what the market maker may do with any tokens it receives. Details are on our market making service page.
Price Trackers and Aggregators
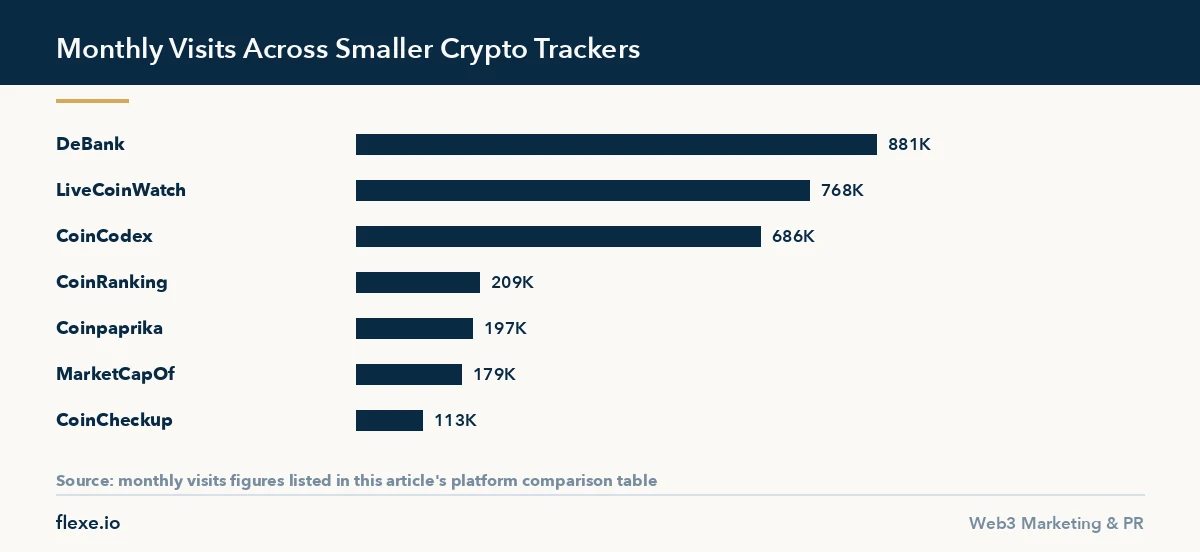
A crypto token listing on an exchange puts it where it can be traded. Tracker listings and other coin listing platforms put it where it can be found. Both matter, and they are bought separately – a tracker will list a token that trades on only one exchange, while an exchange will not. A free listing crypto exchange or a free token listing exchange usually means a venue with little volume. How to list a token on exchange books that matter, and how to list your token on exchange venues with real depth, comes down to liquidity and proof, which is what listing on crypto exchanges is actually bought with.
| Platform | Monthly visits | What a listing gives you |
|---|---|---|
| CoinMarketCap | 38.3M | The reference price feed most other sites pull from |
| StockTwits | 12.2M | A retail investor audience outside crypto-native sites |
| CoinCodex | 686K | Price pages that rank well on long-tail token queries |
| DeBank | 881K | Portfolio integration; the token shows in users’ wallets |
| LiveCoinWatch | 768K | Trending placement, refreshed frequently |
| CoinRanking | 209K | Fast approval; useful early while other listings are pending |
| Coinpaprika | 197K | Detailed asset pages with team and roadmap fields |
| CoinCheckup | 113K | Scoring and analysis pages |
| MarketCapOf | 179K | Comparison pages – “X with the market cap of Y” |
CoinMarketCap and CoinGecko are handled separately because their review processes are stricter and slower than the rest – see CoinMarketCap fast track listing and CoinGecko fast track listing. The smaller trackers above are usually approved within days and are worth doing first, because several of them feed data to larger aggregators.
What a crypto exchange listing requires
Application forms for listing cryptocurrency on exchange platforms differ from venue to venue, but the questions behind them repeat. A review team is settling three things: whether the entity behind the token can be identified, whether the token behaves the way its documentation claims, and whether listing it creates a compliance problem the exchange has to answer for later. Every field on the form maps to one of those three. Reading a form that way explains why a half-finished answer stalls a file for weeks. The reviewer cannot close their own checklist item, so the application simply waits, and nobody writes to tell you that.
Documents the exchange asks for
The document set is heavier than most teams expect on a first attempt, and assembling it usually takes longer than the review itself. Gathering it in one pass, before a single form is opened, is the difference between one round of questions and four.
- Corporate papers: certificate of incorporation, register of directors and shareholders, and proof of address for the entity that will sign the listing agreement.
- Identity documents for founders and for anyone holding a controlling share, normally a passport plus a recent utility bill or bank statement.
- Token documentation: whitepaper, audit report with the commit hash it was run against, verified contract source, and deployment addresses on every chain the token exists on.
- Supply and vesting: total, circulating and locked amounts, the wallet addresses holding each tranche, and the date each tranche is released.
- A legal opinion on how the token is classified in the markets the exchange serves, which some venues require outright and others accept in a lighter form.
- Operational contacts: a technical contact for the integration and a named person who answers the review team the same working day.
Jurisdiction and compliance questions
Jurisdiction decides more applications than technology does. An exchange serving users in a market where the token could be read as a security will ask for an opinion letter, and failing that will decline quietly rather than explain. A registered entity, sanctions screening on the founders, and treasury funds that do not trace back to a mixer are all checked, and none of it is open to discussion once it has been flagged. Where a project is registered somewhere a venue avoids on principle, the useful answer is to pick different venues rather than spend two months arguing with a compliance desk that has already decided.
Technical integration requirements
The technical side is short but blocking. The exchange needs a node it can sync or a public endpoint it trusts, an explorer that resolves transactions, and confirmation rules it can apply safely to deposits and withdrawals. Tokens with unusual mechanics create real work on their side: rebasing supply, transfer taxes, blacklists, pausable transfers and open mint functions all break the internal accounting an exchange runs, and each one has to be disclosed and then handled in their code. A transfer tax on an otherwise standard contract is the single most common reason a clean file is turned down on technical grounds.
How a listing application moves
Almost all of the calendar is spent before anything is submitted, which is the opposite of what most teams plan for. The review itself is short when the file is complete and endless when it is not.
Order of steps and realistic timing
- Shortlisting venues against the token’s real market, region and pair plan: a few days, and the point at which an unsuitable exchange should be dropped rather than tried anyway.
- Assembling documents and reconciling supply against the chain: one to three weeks, driven almost entirely by how fast the project returns papers.
- Submission and first review: usually one to four weeks of silence, longer around a venue’s own product releases or a market-wide event.
- Follow-up questions: one or two rounds, each closed on the same working day from our side.
- Commercial terms, then technical integration and a deposit window before trading opens: one to two weeks once terms are signed.
Anyone quoting a fixed decision date is quoting something they do not control. What can be committed to is a submission that is complete on the first pass and a follow-up answered within the day, and that is most of the difference between six weeks and four months.
What the client prepares
Four things on the project side account for most of the delay we see, and all four can be settled in a week if someone owns them.
- One decision maker who can sign and who replies within a day. An application with three approvers moves at the speed of the slowest one.
- A single canonical set of numbers for supply, allocation and vesting releases that matches the site, the whitepaper and the chain without anyone having to explain the difference.
- Brand assets at the dimensions each venue specifies, plus a short English description that reads as a factual summary rather than promotion.
- Funds for the venue fee and, where required, the opening liquidity or market making float, available before terms are signed rather than promised after.
- A launch date you intend to keep. Across our own campaign data, a firm date moves median net ROI from 1.4x to 3.1x, mostly because everything else can then be scheduled around it.
Crypto token listing fees and what moves them
Exchange fees are set by the exchange and vary more than any other number in this process. Large venues price in the six figures and often ask for part of it in their own token; mid-tier venues sit far below that; some regional venues charge little at listing and make their money on the market making arrangement instead. Our own fee for a crypto exchange listing is separate and covers preparation, submission and the follow-up work, not the venue’s charge. We say which is which in writing before anything starts, because conflating the two is how projects end up short of funds at the terms stage.
What moves the exchange’s number: volume the token already trades elsewhere, the depth the book can hold from day one, whether the venue wants exposure to your region, and how much of the integration work falls on their engineers. What does not move it is community size or the quality of a deck. For context on the wider budget, our campaigns start at $4,000 for a single focused channel, while a full launch across listings, media and creator work generally runs $50K to $500K over three to six months.
What we will not sell you
Guaranteed daily trading volume from a market maker is sold openly in this market. It describes wash trading, exchanges detect it, and the result is a delisting that other venues can see when you apply to them next. We decline that work. Market making as we run it means quoting two-sided prices against a spread and depth target with real inventory at risk, and no promise about how much of it trades on any given day.
We also do not promise approval. The decision belongs to the exchange, and the honest description of our role is that we prepare the file, submit it and answer the review. Across more than 800 campaigns since 2018 that has made the process predictable rather than certain: on the 150 campaigns where we measured outcomes end to end, the disclosed failure rate is 12 percent, and we publish it for the same reason we publish the median.
How the result is judged
A coin listing on exchange venues judged only by its announcement is judged badly. The measures that still mean something a quarter later are the depth the book holds at one and two percent from mid price, the share of volume that is not the market maker’s own, how many holders arrived through that venue, and whether the pair is still quoted after ninety days. Against our own baseline, median net ROI across 150 campaigns was 2.8x within ninety days, with a range from 1.4x to 7.0x. Tokens that listed before there was any demand to meet sat at the bottom of that range with fairly grim consistency.
Who this is not for
If the token has no audit, no verified contract, or a supply table that cannot be reconciled against the chain, exchange work is premature and we will say so on the first call rather than bill for a file that will fail. If the plan depends on a guaranteed volume number, we are the wrong agency for it, and no crypto exchange listing bought on that basis survives the first audit a venue runs. If the budget covers the venue fee and nothing else, tracker listings and a launch campaign are the better first purchase, and the CoinGecko fast track listing service is usually where that sequence starts.
Get a free exchange listing plan
Send the token, chain and the exchanges you have in mind to Flexe.io on Telegram. Within 24 hours we return a free plan: which tier fits now, what the document set is missing and the realistic timing for each venue. We will say plainly if a venue is out of reach today.
Frequently Asked Questions
How long does a crypto exchange listing take?
From a few weeks to several months. Smaller exchanges can list a prepared token within weeks, while top-tier venues review trading history, holders and liquidity elsewhere first. Most of the delay comes from incomplete documents and slow answers to follow-up questions, so a complete file with reconciled supply figures shortens the timeline more than anything else.
Is there free listing on a crypto exchange?
Some exchanges publish no listing fee, and free listing crypto exchange offers do exist on smaller venues. The real costs sit elsewhere: market making, liquidity, audits, legal review and the marketing that brings traders. Be wary of anyone selling a guaranteed listing for a fixed fee paid to a third party rather than the exchange.
How to list a token on an exchange as a new project?
Start with the document set and a working market on a DEX, then apply to exchanges that match your stage instead of the largest names. Each venue reads the form, the contract and the trading data. Our guide to the CEX listing application walks through the steps, and Binance has its own route for founders.
Does a coin listing on exchanges require a market maker?
Most serious exchanges expect one and ask about it in the application. A market maker keeps spreads tight and the order book usable from the first hour of trading. Arrange the agreement before applying, put its terms in writing, and check what it may do with any tokens it receives as part of the deal.
What happens if an exchange declines the application?
Ask what was missing, fix it and decide whether to reapply later or move to a venue that fits the current stage. Declines usually come from inconsistent supply figures, a missing audit or too little trading history. A decline is rarely permanent, but reapplying with the same file almost always produces the same answer.