A Web3 pitch deck from Flexe is the one file that has to survive a 3 minute read from an investor who sees 10 of them a week, and you get the structure, the writing, the design and a revision pass after real funds have seen it. Flexe has run more than 800 campaigns for crypto projects since 2018. This page covers how the work runs, what you supply, what it costs, and how the result is judged.
Why a High-Quality Web3 Pitch Deck is Crucial
Funds read for reasons to stop. A well-structured deck answers the problem, the market, the model and the team before those questions are asked, which is the whole job. We build decks that hold up under that reading rather than decks that look good on a screen.
What We Offer in Our Web3 Pitch Deck Service
Every deck we build carries the same six parts:
- Professional Design: Visually appealing and brand-aligned slides that capture attention.
- Compelling Storytelling: A structured narrative that highlights your problem, solution, market opportunity, and revenue model.
- Market Research & Data Insights: Precise metrics and research-backed projections to instill investor confidence.
- Tokenomics & Roadmap: Clear visualization of token utility, distribution, and future growth plans.
- Competitive Analysis: Insights into your competitors and how your project stands out.
- Call-to-Action (CTA): A strong closing that drives investors toward engagement.
Additional Packaging Services
Most projects need more than the deck. We also build the landing page investors open straight after it, the white paper that carries the technical, financial and strategic detail, and the promo video used at events and in outreach. Each is priced on its own, and none of them is a condition of the deck.
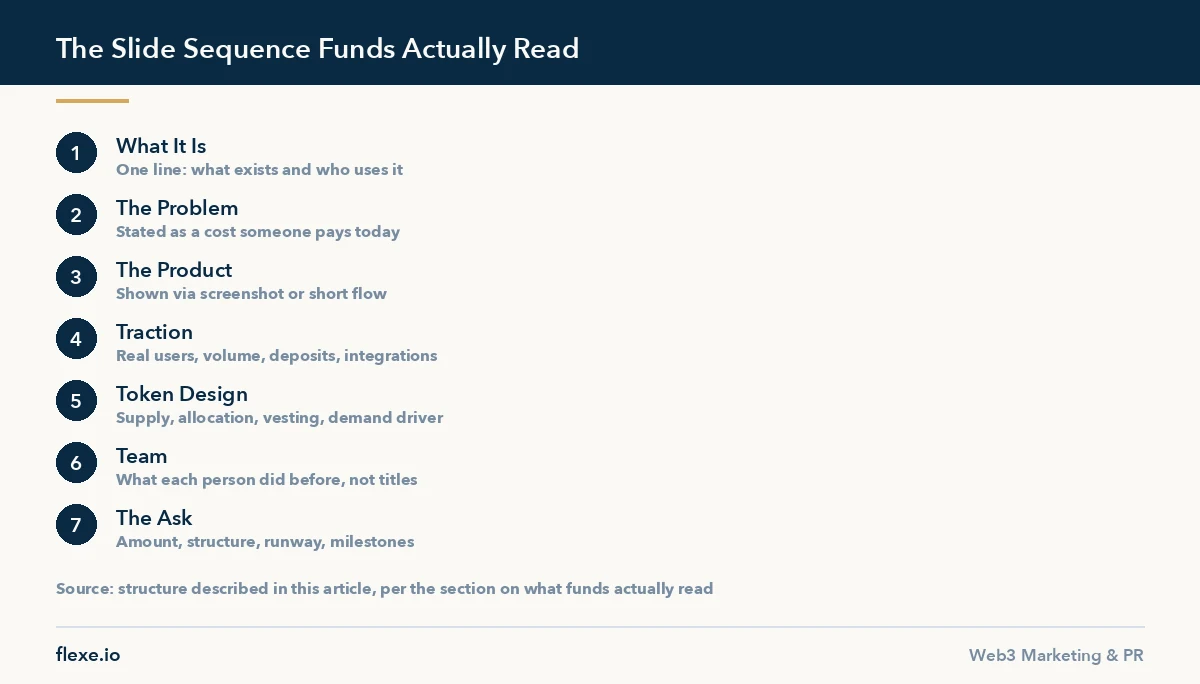
The structure funds actually read
An investor opens a deck, spends about three minutes on it, and is deciding one thing: whether to take a call. Everything in the deck either helps that decision or delays it.
- What it is, in one line. Not the vision. The thing that exists, or will exist, and who uses it.
- The problem, stated as a cost someone currently pays. Abstract problems produce abstract interest.
- The product, shown. A screenshot or a short flow beats a paragraph describing an interface.
- Traction. Whatever is real: users, volume, deposits, integrations, waitlist. Small and true outperforms large and unverifiable.
- Market, sized from the bottom up. Top-down slices of a trillion-dollar figure are the fastest way to lose a technical reader.
- Token design, if there is a token. Supply, allocation, vesting and what creates demand. This slide is read closely and is where most decks fall apart.
- Team, with what each person did before. Names and history, not titles.
- The ask, and what it buys. Amount, structure, runway, and the milestones the round is meant to reach.
What we build and how
We work from a founder session rather than a form. The first pass is structure and narrative in plain text, because a deck that is designed before its argument is settled has to be redesigned. Once the argument holds, it becomes a designed deck, plus a short version for cold outreach and a longer appendix for the diligence questions the short version will provoke.
The token and supply slide is checked against the contract and the public trackers rather than the internal spreadsheet. A deck whose numbers do not match the chain is caught at exactly the wrong moment. The reconciliation method is set out in how to prepare a tokenomics page.
What we need from you
Access to a founder for a working session, whatever traction data exists in raw form, the current supply and vesting position, any existing deck however rough, and the names of the funds you intend to approach. That last item changes the emphasis more than anything else, because a technical fund and a generalist fund read the same deck differently.
Common failures we correct
Forty slides where twelve would do. A market size that would be impressive if it were reachable. Partner logos that describe conversations rather than agreements. A roadmap of quarters with no delivered items behind it. A token section that avoids the vesting schedule. Each of these is read as a signal about the team rather than about the slide.
The most common structural error is opening with the vision and reaching the product on slide nine. By then the reader has decided.
Stage by stage with timing
The first week is spent on the argument, not on slides. A recorded working session with a founder, around two hours, produces the spine: what exists today, who uses it, what the round buys. Within three working days you get the whole thing back as plain text, slide by slide, with every number marked as verified, claimed, or missing. Most of the disagreement happens at that point, which is the cheapest place for it to happen.
Design starts once the text is signed off, normally days four to ten. You see a styled version of four slides first, so the visual direction is settled before twenty slides are built on it. The full designed set follows, together with the short version made for cold outreach and the appendix that answers the questions the short version provokes.
From brief to a set you can send is about two to three weeks for a project whose data is in order, and four to five weeks where traction has to be pulled out of dashboards and the token schedule is still moving. A fixed deadline, a demo day or a fund’s closing date, is worth telling us at the start, because a date forces decisions that otherwise drift for months.
What you supply
The material below is what keeps the schedule. None of it needs formatting first.
- A founder available for one recorded session, plus a named person who can answer follow-up questions inside a working day.
- Raw traction data exactly as it exists: exports, dashboard screenshots, contract addresses, analytics logins.
- The current supply position: total supply, the allocation table, vesting terms, and any tranche already in circulation.
- Any earlier deck, memo or one-pager, however rough, plus whatever feedback investors gave on it.
- The list of funds and angels you intend to approach, with the ones you have already spoken to marked.
- Structure and jurisdiction detail if the raise has one: a SAFT, an equity wrapper, a foundation.
Missing items do not stop the work, they change what the deck is allowed to claim. A traction slide without an export becomes a claim rather than evidence, and readers at technical funds treat those two things very differently.
What the working session covers
One recorded session, roughly two hours, settles the material that the rest of the work depends on. It is not a briefing call and it is not run from a form.
- What exists today, described without adjectives, and who is using it right now.
- The cost someone currently pays for the problem, stated as money or time rather than as a trend.
- Which traction numbers are defensible, which are directional, and which should not appear at all.
- How the round is structured, what it buys, and which milestones it is meant to reach.
- Which funds have already passed, and the exact reason each gave, because that is the cheapest research available.
The recording goes to the writer rather than being summarised, since the phrasing a founder uses when explaining the product to a peer is usually better than anything written afterwards.
Revision rounds you get
Two rounds are included and they deliberately sit at different stages. The first is on the text, where structure and wording change freely and nothing costs design time. The second is held until after the deck has gone to a handful of investors, because the questions that come back are the real specification for the appendix. Revising a deck nobody has read yet is guesswork dressed up as iteration.
Further rounds are billed hourly or as a small fixed scope. In practice the projects that need a third and a fourth round are the ones where the raise itself changed: a different round size, a new lead investor, a product pivot. That is a new brief rather than a revision, and pricing it as one keeps both sides honest.
Formats and handover
- The full deck as an editable file in Figma or Google Slides, whichever your team actually uses, plus a flattened PDF for sending.
- A short version, usually ten to twelve slides, built for cold outreach and for being forwarded inside a fund.
- An appendix set covering the token schedule, security and audits, competitive detail and financials.
- Editable source files for every chart and diagram, so your team can update a number without coming back to us.
- Fonts and colour values, with licence-safe substitutes named where a typeface cannot travel with the file.
You own all of it. Nothing stays behind an account of ours, and the editable file is handed over with edit rights rather than view rights.
How the price is set
Quoting starts from scope rather than slide count, because fifteen slides for a project with audited numbers is far less work than fifteen slides where the numbers have to be reconstructed first. A focused single piece of work at this agency starts at $4,000, and deck work sits near that floor when the material is ready and the story is already settled. Where the deck is one part of a launch programme, the wider range is $50K to $500K over three to six months.
What moves the quote, in rough order of impact:
- Whether traction data exists in a verifiable form, or has to be rebuilt from raw logs and exports.
- Whether the token model is final. A supply table that changes twice rewrites several slides and the appendix each time.
- Illustration load. Custom diagrams, product mockups and animated transitions are each separate production work.
- Number of audiences. A technical fund and a generalist fund read the same deck differently, and a second cut is a second pass rather than a find and replace.
- Turnaround. A week of calendar time compressed into three days is paid for in overtime and priced that way.
How the result is judged
The measure is meeting conversion, not compliments. Count decks sent, replies received, and first calls booked. A well-matched list of forty funds that returns nothing has told you something specific, and it is almost always the first three slides rather than the design.
The second measure is the shape of the questions you get back. Questions about market size or release schedules mean the deck moved the reader into diligence. Questions about what the product actually does mean slide two failed. We ask clients to forward replies verbatim, because a paraphrase loses the exact wording that shows where the reader stopped following.
Where decks quietly fail
The failure patterns repeat across hundreds of projects. A deck built to be presented aloud and then sent as a file, so half the argument lives in the speaker and never arrives. Product screenshots at a resolution that turns to mush on a laptop. A team slide padded with advisers who have not answered an email in six months. Partner logos with no agreement behind them, which an analyst verifies in ten minutes and remembers longer than that.
The expensive one is a token slide that omits the vesting schedule. Readers assume the worst when a number is missing, and the assumption is usually harsher than the truth would have been. Supply and allocation are checked against the contract and the public trackers before the slide is designed. The same discipline applies to the longer document a fund asks for next, which is covered on our white paper page.
Who this is not for
A deck does not repair a raise with no product and no team history behind it. If the honest answer to what exists today is a landing page and a Telegram channel, the money is better spent building something to show, because the first reply from any fund asks for the demo and the absence of one ends the thread.
It is also the wrong purchase if you are raising from retail rather than from funds. Retail attention is bought with public evidence: coverage, a working token page, visible community activity. That work is described on our crypto PR page. And if you want a guarantee, we do not sell one. Across the campaigns we measure, a disclosed 12 percent do not return their cost, and fundraising material is no different: the outcome depends on the round, the market and the team far more than on the file.
After the raise the work turns into reporting, and our guide to investor relations for crypto projects sets out what to send and how often.
What Comes After the Deck
A deck opens a conversation. What sustains it is public evidence that the project is real, which is where media coverage and a credible token page do the work. Those are covered on our crypto PR page. Pitch deck scope and terms are available on request.
Frequently Asked Questions
What does a Web3 pitch deck cost?
It depends on how much of the story already exists. A deck built from a finished narrative and real numbers is a smaller job than one where the positioning is still being argued out. We quote after the first call, once the scope and the slide count are settled, and that figure does not move afterwards unless you change the scope.
How long does a pitch deck take?
Two to three weeks is typical for a seed deck when the material is ready. Structure and narrative come first, then design, then a revision pass after real investors have read it. If the tokenomics are unresolved the deck waits, because no design fixes a model that does not hold.
Will a better deck get us funded?
No, and anyone promising that is selling something. Across the 150 campaigns in our own benchmark a disclosed 12 percent do not return their cost, and fundraising material is no different: the round, the market and the team decide the outcome far more than the file does. A good deck removes reasons to say no.
Do you write the content or only design it?
Both, and the writing is the larger half. We build the structure and the narrative first, then design against it, because a deck with a weak argument fails in the same 3 minute read as an ugly one. You supply the numbers, the model and the team detail, and we do the rest.
Get Your Pitch Deck Today!
Send the stage, the round size and whatever material exists, and you get back the scope, the slide count and the fee before any work starts. Message us on Telegram.