RWA tokenization platforms held $33.07 billion of tokenised assets on 20 September 2026, and five of them held half of that: Securitize ($4,525.7 million, the venue behind BlackRock BUIDL), Ondo ($3,360.8 million), Tether ($3,126.2 million, all of it gold), Spiko ($2,629.2 million in money market funds) and Circle ($2,506.2 million). Figures read today from DefiLlama’s RWA dashboard, tokenised assets only, without stablecoins, governance tokens or perpetuals.
What RWA tokenization platforms do
A platform in this category takes an asset that exists off chain, a Treasury bill, a fund share, a bar of gold in a vault, a pool of private credit loans, and issues a token that stands for a legal claim on it. The work is mostly not the token. It is the legal wrapper, the custodian or transfer agent, the list of who may hold the thing, and the path back to the underlying.
Two jobs hide inside that description, and different companies often do them. Securitize is an issuance platform and transfer agent: BlackRock, KKR and others put their funds on it, and the fund stays theirs. Tether and Paxos issue a single product of their own and hold the metal behind it. Ondo, Spiko and Franklin Templeton do both at once. That split is why the same name shows up as a platform in one ranking and as a fund in the next.
The largest RWA tokenization platforms in 2026, ranked by value on chain
Ordered by the dollar value of tokenised assets each platform has live on chain, read 20 September 2026. The ten below hold 75.1% of a $33.07 billion total spread across 136 platforms and 2,372 tokenised assets.
1. Securitize (issuance platform and transfer agent)
The biggest venue in the market, and the one most published lists skip, being plumbing rather than a brand. BlackRock BUIDL is $2,312.0 million of it; KKR, Blockchain Capital and two dozen other products are the rest.
- Value on chain: $4,525.7 million, 13.68%
- Main asset class: money market funds
- Chains: 14
- Who can invest: permissioned, institutional and qualified investors after onboarding
2. Ondo (yield tokens, Treasuries and tokenised stocks)
The widest product range here. Its US Dollar Yield token is $2,244.4 million of the platform total, and its own page states the terms: eligibility is non-US individuals and organizations, backing is bank deposits and short-term US Treasuries. OUSG adds $135.5 million.
- Value on chain: $3,360.8 million, 10.16%
- Main asset class: money market funds and yield tokens
- Chains: 16, the widest spread in the top ten
- Who can invest: mixed, most of the value sits in permissioned products
3. Tether (gold)
Tether Gold is $3,091.6 million of the $3,126.2 million, one troy ounce of physical gold per token. It is the largest tokenised product anyone can buy without an allowlist.
- Value on chain: $3,126.2 million, 9.45%
- Main asset class: gold
- Chains: 10
- Who can invest: permissionless to hold, redemption against metal has its own terms
4. Spiko (European money market funds)
Spiko is the clearest case of regulation as the product feature: it names its supervisor in its own description. Its largest fund, an Amundi overnight swap fund in euros, is $1,408.6 million, the biggest euro-denominated entry here.
- Value on chain: $2,629.2 million, 7.95%
- Main asset class: money market funds, US and Eurozone T-bills
- Chains: 7
- Who can invest: permissioned, onboarding under European fund rules
5. Circle (permissioned yield)
One product, USYC, carries the whole $2,506.2 million. It is a yield instrument for institutions, not a retail token.
- Value on chain: $2,506.2 million, 7.58%
- Main asset class: money market fund
- Chains: 3
- Who can invest: permissioned only
6. Franklin Templeton (BENJI)
The oldest tokenised money market fund line from a traditional asset manager. The institutional share class alone is $1,523.4 million, across nine chains.
- Value on chain: $2,277.4 million, 6.89%
- Main asset class: government money market funds
- Chains: 9
- Who can invest: permissioned, share class decides the minimum
7. Maple (private credit)
The largest credit book here and one of two permissionless names in the top ten. Syrup USDC is $1,246.9 million of it. Credit is where the risk changes: yield comes from borrowers, not a government bill.
- Value on chain: $1,891.3 million, 5.72%
- Main asset class: credit pools
- Chains: 9
- Who can invest: permissionless for the main pools
8. Paxos (gold)
One product on one chain, still in the top ten. The PAX Gold page states the mechanics: each token is backed by one fine troy ounce in LBMA vaults in London, held in custody by Paxos Trust Company, and the holder owns the metal.
- Value on chain: $1,882.9 million, 5.69%
- Main asset class: gold
- Chains: 1
- Who can invest: permissionless to hold, KYC at the issuer for mint and redemption
9. Centrifuge (funds for asset managers)
Centrifuge tokenises portfolios someone else manages. The Janus Henderson Anemoy AAA CLO fund is $1,019.0 million of the total, so one manager decides most of what this platform is worth.
- Value on chain: $1,405.8 million, 4.25%
- Main asset class: corporate bond and CLO funds
- Chains: 8
- Who can invest: permissioned, fund by fund
10. WisdomTree (tokenised fund platform)
Another traditional asset manager missing from crypto-side rankings. Almost the whole book, $1,230.2 million, sits in one Treasury money market digital fund. Behind it: Libeara $794.6 million, bStocks $643.1 million, Superstate $627.0 million, Hastra $592.5 million.
- Value on chain: $1,233.9 million, 3.73%
- Main asset class: money market funds
- Chains: 6
- Who can invest: permissioned
| Platform | Asset class | Chains | Value on chain, 20 September 2026 | Who can invest |
|---|---|---|---|---|
| Securitize | Money market funds | 14 | $4,525.7M | Permissioned |
| Ondo | Yield tokens, Treasuries, stocks | 16 | $3,360.8M | Mixed |
| Tether | Gold | 10 | $3,126.2M | Permissionless |
| Spiko | Money market funds | 7 | $2,629.2M | Permissioned |
| Circle | Money market fund | 3 | $2,506.2M | Permissioned |
| Franklin Templeton | Government money market funds | 9 | $2,277.4M | Permissioned |
| Maple | Private credit | 9 | $1,891.3M | Permissionless |
| Paxos | Gold | 1 | $1,882.9M | Permissionless |
| Centrifuge | Corporate bond and CLO funds | 8 | $1,405.8M | Permissioned |
| WisdomTree | Money market funds | 6 | $1,233.9M | Permissioned |
Asset classes: treasuries, credit, gold, real estate
The category is several markets sharing a label, and the sizes are lopsided. On 20 September 2026 bonds, meaning Treasuries and money market funds, are $17,214.0 million or 52.05% of the total. Precious metals are $6,169.7 million or 18.65%, private credit $4,182.1 million or 12.64%, public equities $2,436.8 million or 7.37%, private equity and venture $1,290.5 million or 3.90%, reinsurance $590.7 million or 1.79%.
Real estate is the surprise. It is the asset class every explainer opens with, and on chain it is $28.06 million, or 0.08% of the market. Tokenised property has not failed technically; it has failed to find buyers, because transferring a building legally does not compress into a token the way a fund share does.
The 4 September reading told the same story with a different boundary: treasuries and money market funds $11.24 billion or 40.7%, gold $5.05 billion or 18.3%, funds and private credit most of the rest, and Ondo Global Markets at $961 million the only listed-stock entry in the top ten.
How to pick a platform: custody, redemption, audits, minimum, jurisdiction
Size tells you the market trusts a venue, not whether you can use it. Five questions separate the products that work for a buyer from the ones that are large and unreachable.
- Custody. Who physically holds the asset, and under what licence. Paxos names Paxos Trust Company and LBMA vaults for PAX Gold; a fund platform names a transfer agent and a custodian bank. If no named entity appears, the claim is weaker than the token implies.
- Redemption. Whether you can exchange the token for the underlying, on what notice and at what fee. Tether Gold and PAX Gold redeem against metal on the issuer’s terms; most permissioned fund tokens redeem at the fund’s dealing cycle, not instantly.
- Attestations and audits. Reserve attestations for metal, fund reporting for share classes. Frequency matters more than the existence of a document.
- Minimum and access model. $20.80 billion of the market, 62.9%, is permissioned: an allowlist and onboarding before you may hold the token. Only $12.28 billion, 37.1%, is permissionless, and gold plus the Maple credit pools carry most of that.
- Jurisdiction. Ondo’s page limits its yield token to non-US individuals and organizations; Spiko is supervised in Europe. The token travels anywhere, the right to hold it does not.
If you run a project here, not just research one: RWA is the one crypto category where institutional press still moves the needle, because the counterparties read it. We place that coverage in outlets their compliance teams already accept. PR placements in crypto media.
Risks and what is not solved
Value on chain is a size measure and nothing more. It does not say whether redemption works under stress, who holds custody, what the fee is, or whether a retail buyer can reach the product. Several of the largest entries are open only to qualified investors, which makes them large and irrelevant at the same time.
Concentration is the second problem. One manager stands behind $1,019.0 million of Centrifuge’s book, one fund behind $1,230.2 million of WisdomTree’s. A platform total that looks like a market is often a single product with a single counterparty. Private credit adds borrower risk, and recovery on a defaulted loan runs through courts, not code.
Chain count is not distribution either. The median product in the 4 September top ten was live on four chains, with a spread from one to twelve. Ondo Yield Assets reached twelve networks with $2.53 billion while Tether Gold sat on Ethereum alone with $3.12 billion, more than any multi-chain product in that table. Paxos still holds $1,882.9 million on one chain. Assets follow distribution agreements and regulatory permissions; extra chains widen who may hold a token without bringing balances. The same effect shows in our list of the top 30 decentralized exchanges.
How this ranking was built
One number decides the order: the dollar value of assets a platform currently has tokenised on chain, read from DefiLlama’s RWA data on 20 September 2026. Stablecoins, governance tokens, perpetuals and flagged entries are left out, giving $33.07 billion across 2,372 tokenised assets and 136 platforms. Chain counts are the networks each platform has value on; the access model is the source’s own label.
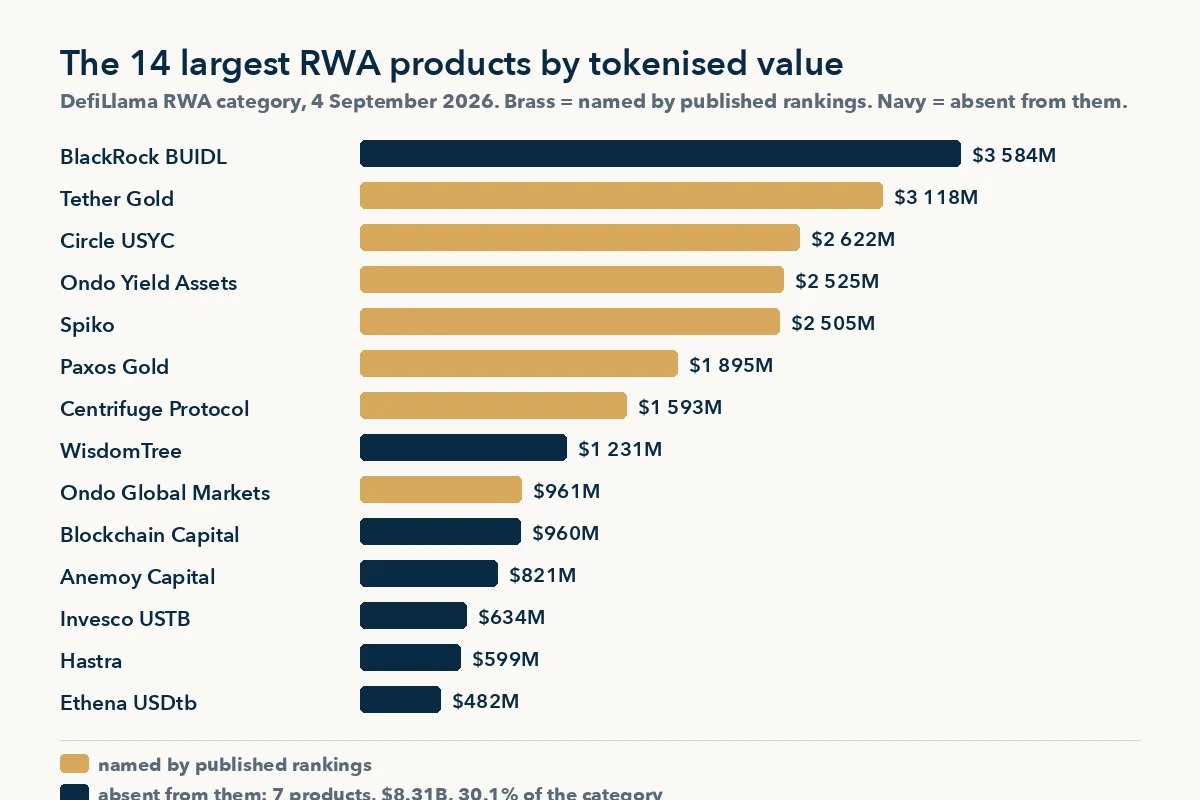
The first reading of this page used DefiLlama’s RWA protocol category on 4 September 2026: 156 protocols, $27.59 billion, ten platforms holding $20.99 billion or 76% of it, BlackRock BUIDL largest at $3.58 billion. Both readings are kept because the boundary changed, not only the numbers. Excluded on purpose in both: stablecoins that hold reserves but tokenise nothing for an investor, bridging and messaging infrastructure, and anything whose value is a protocol token rather than an underlying asset. We did not score quality, custody or redemption terms, none of which is comparable from public data.
| Platform | Tokenised assets | Share of category | Chains | What is tokenised |
|---|---|---|---|---|
| BlackRock BUIDL | $3,584M | 13.0% | 8 | Institutional digital liquidity fund |
| Tether Gold | $3,118M | 11.3% | 1 | Physical gold, one troy ounce per token |
| Circle USYC | $2,622M | 9.5% | 4 | Permissioned yield product |
| Ondo Yield Assets | $2,525M | 9.2% | 12 | Short-term US Treasuries |
| Spiko | $2,505M | 9.1% | 7 | Money market funds, US and Eurozone T-bills |
| Paxos Gold | $1,895M | 6.9% | 1 | Physical gold in LBMA vaults |
| Centrifuge Protocol | $1,593M | 5.8% | 10 | Tokenised funds for asset managers |
| WisdomTree | $1,231M | 4.5% | 2 | Tokenised funds platform |
| Ondo Global Markets | $961M | 3.5% | 3 | Equities on chain |
| Blockchain Capital | $960M | 3.5% | 1 | Fractional interest in a venture fund |
The gap against published rankings is the reason this page exists. Seven of the fourteen largest products by tokenised value, holding $8.31 billion between them, appeared on none of the lists we checked: BlackRock BUIDL, WisdomTree, Blockchain Capital, Anemoy Capital, Invesco USTB, Hastra and Ethena USDtb. That is 30.1% of the category missing from the summary of it, including the largest single product. Those lists also include infrastructure that tokenises nothing. A list assembled from other lists inherits that selection and rarely re-measures. Our own number will age the same way, which is why the method sits here.
If you are taking a token to market rather than buying one, the adjacent questions are covered in marketing an RWA or stablecoin product and in our notes on getting listed on CoinGecko and CoinMarketCap.
Frequently Asked Questions
What are the largest RWA tokenization platforms in 2026?
By value on chain on 20 September 2026: Securitize at $4,525.7 million, Ondo at $3,360.8 million, Tether at $3,126.2 million, Spiko at $2,629.2 million and Circle at $2,506.2 million. Those five hold 45.8% of a $33.07 billion market spread over 136 platforms.
How big is the tokenized real-world asset market?
$33.07 billion of tokenised assets on 20 September 2026, across 2,372 assets and 136 platforms, once stablecoins and governance tokens are removed. The ten largest platforms hold 75.1% of it. Totals differ between trackers because each draws the boundary differently, so any figure needs its source and date.
Which assets are actually being tokenized?
Bonds, meaning Treasuries and money market funds, are $17,214.0 million or 52.05% of the market. Precious metals are $6,169.7 million, private credit $4,182.1 million, public equities $2,436.8 million. Real estate, the class most explainers open with, is $28.06 million, or 0.08% of the total.
Can a retail investor buy tokenized real-world assets?
Only part of the market is reachable. $20.80 billion, or 62.9%, is permissioned and needs onboarding and an allowlist before you may hold the token. The remaining $12.28 billion, or 37.1%, is permissionless, and gold plus the Maple credit pools are most of it.
Does a platform on more chains hold more assets?
No, and the figures show the opposite. Paxos holds $1,882.9 million on a single chain, Circle $2,506.2 million on three. On 4 September, Tether Gold held $3.12 billion on Ethereum alone, more than Ondo Yield Assets held across twelve networks.
Why do published RWA rankings disagree with this one?
Because most rank recognition rather than assets. Seven of the fourteen largest products, holding $8.31 billion or 30.1% of the category, appeared on none of the lists we compared against, including the largest single product. Lists built from other lists inherit that selection and rarely re-measure.
Related reading
Where tokenised assets trade once issued: our ranking of DEX aggregators by routed volume.